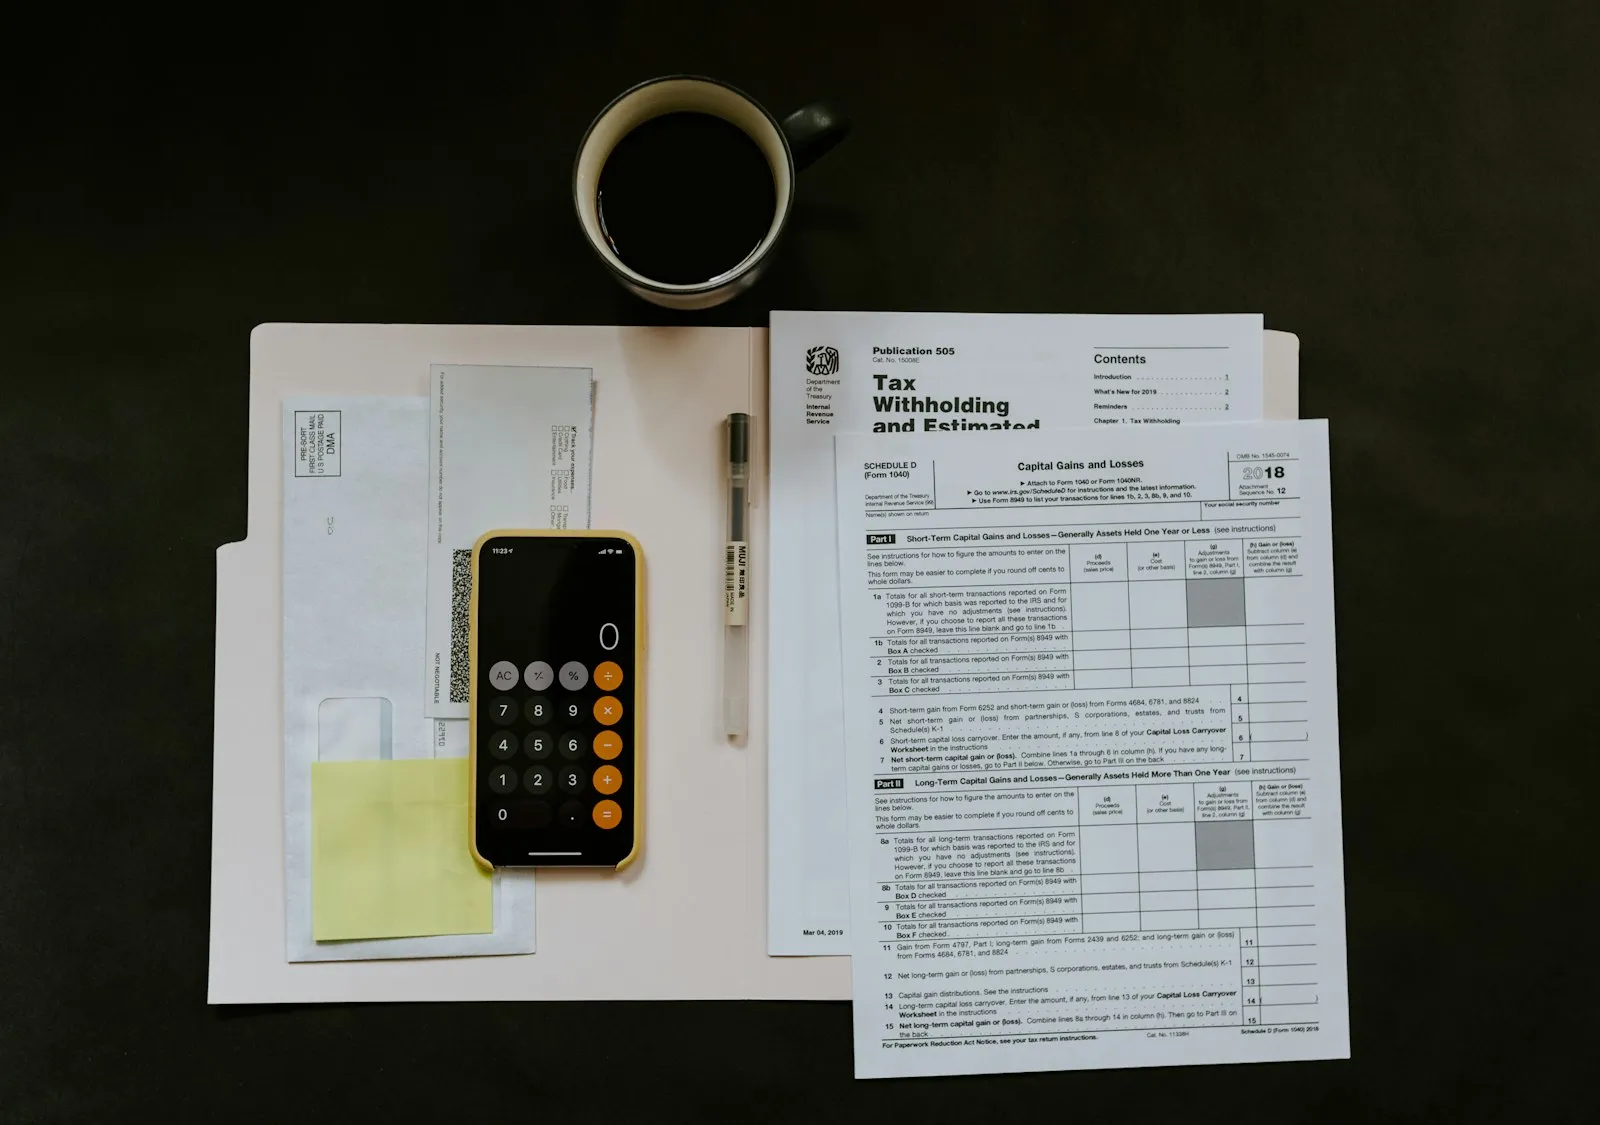
ever be caught out by a tax bill again. A simple set-aside method for freelancers and creatives, plus the habits that make it automatic.
Featured in this article
THE COUNT.
There's a particular kind of dread that only self-employed people know. It arrives with an official envelope or email, and a number you weren't quite ready for.
The frustrating thing is that the money was there. It came in over the year, in dozens of payments. It just didn't stay put.
The fix isn't earning more or understanding every line of tax law. It's a simple habit: treat part of every payment as never having been yours.
Step 1: Choose your percentage
Tax rules differ from country to country, and they depend on your income, your expenses and your circumstances. So there's no single right number for everyone.
What many freelancers do is choose one fixed percentage to set aside from every payment. A figure somewhere between 20% and 30% is a common starting point, but the right number for you depends on where you live and how much you earn.
The best way to find it: look up your country's current rates for self-employed income, or spend an hour with an accountant once. It's one of the best-value hours you'll ever pay for.
If in doubt, round up. Having too much set aside is a pleasant surprise. Having too little is not.
Step 2: Separate it immediately
The single most important rule: move the tax money the day you're paid. Not at the end of the month. Not when you remember. The day it lands.
Ideally, keep it in a separate savings account you don't touch for anything else. If it's sitting in your everyday account, it will quietly get spent. Not through carelessness, but because money in view feels like money available.
Step 3: Track what you set aside
Keep a simple log for every payment:
- Date
- Client or source
- Amount received
- Amount set aside for tax
- Running total in your tax pot
This takes thirty seconds per payment, and it means you always know exactly where you stand. No guessing, no end-of-year detective work.
Step 4: Keep your receipts as you go
In many countries, legitimate business expenses can reduce what you owe. But only if you can show them. Log expenses monthly, not annually. A shoebox of faded receipts in the eleventh month is where good intentions go to die.
Step 5: Do a quarterly check-in
Every three months, compare your tax pot with your income so far. Is your percentage still right? Did you have an unusually good quarter? Adjust early, and there are no surprises later.
The real benefit: peace of mind
When your tax is already set aside, your income finally feels like your income. You can plan, spend and save without a background hum of worry. For many freelancers, that calm is worth more than any single invoice.
Built for this: THE COUNT.
THE COUNT. is the money book in our MADE TO LAST. set for solo creatives. It brings together income and expense ledgers, profit and loss, pricing and tax set-asides in one hyperlinked digital planner, so you can see your whole financial picture in one calm place.
Your next step
Pick your percentage today, even if it's a rough one. Then, the next time you're paid, move that amount before you do anything else.
When you want a proper home for your numbers, explore THE COUNT..
This post offers general information, not tax or financial advice. Tax rules vary by country and circumstance, so please check with a qualified accountant or your local tax authority.
Planners for this article
THE COUNT.
The money book from MADE TO LAST. — ledgers, profit and loss, pricing and tax set-asides in one hyperlinked place.
ViewThe Financial Freedom Budget Planner
ViewYour Personal Finances in One Planner
ViewPlan it in Arwign Calendar
Written by
Frank @Arwign
Writes for Arwign Planners about focus, money and building things that last, one calm step at a time.
Explore our planners
Comments (0)
Sign in to join the conversation.
Be the first to comment.